
This week offered a sharp reminder that, even amid a resilient economy, we are not free of the looming shadow of inflation. The latest inflation numbers show a meaningful reacceleration in price pressures. Both the Consumer Price Index (CPI) and the Producer Price Index (PPI) posted their strongest monthly gains in years, signaling renewed cost pressures for households and businesses. For the housing sector, these developments underscore that elevated mortgage rates are the new normal as we move through the spring leasing and homebuying season.
Consumer prices jump as energy and shelter lead upswing
The April CPI report showed a 0.6% month‑over‑month increase, following a 0.9% rise in March. Importantly, consumer prices jumped 3.8% from last year, picking up speed from March’s 3.3% yearly advance.
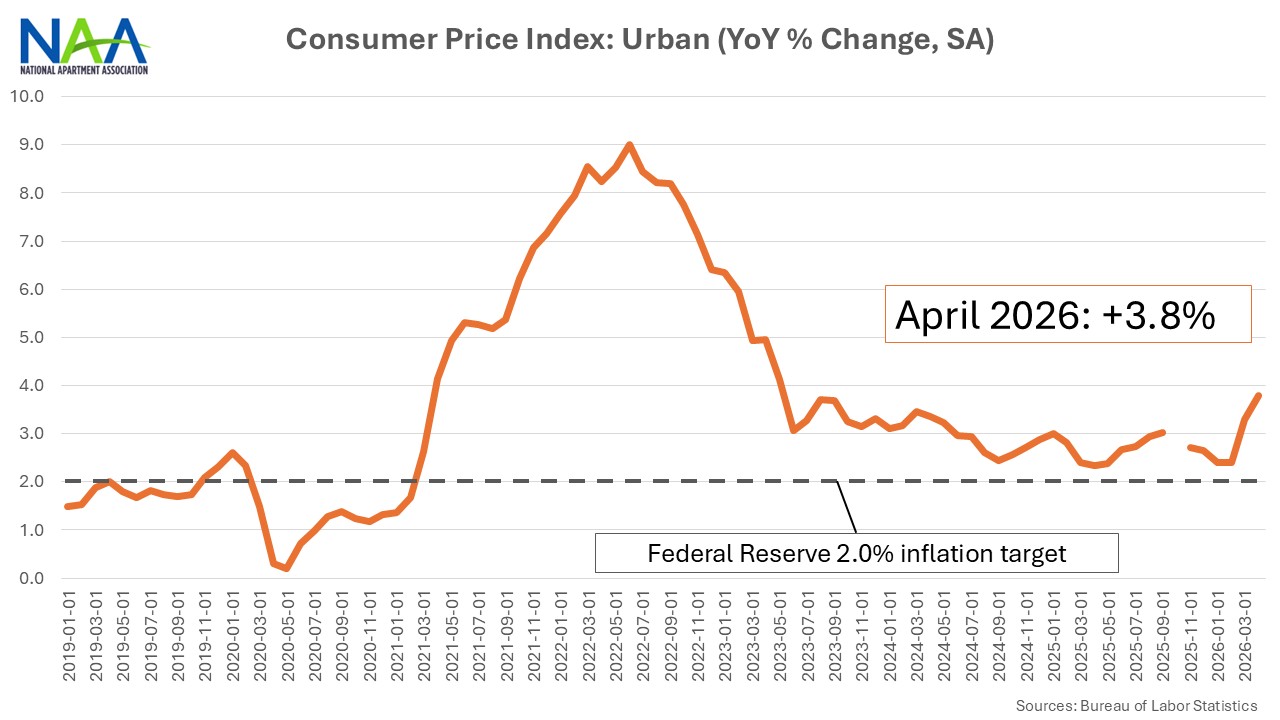
The Iran conflict and the chokepoint in the Strait of Hormuz are impacting global oil prices with clear effects in the CPI data. Energy prices showed the largest year-over-year surge, posting a 17.9% increase, as gasoline prices jumped 28.4% and fuel oil prices rose a striking 54.3% from April 2025. Energy services also increased to the tune of 5.4%, with electricity prices 6.1% higher than last year.
Importantly for real estate markets, the cost of shelter accelerated in April, with a 0.6% monthly gain and a 3.3% yearly increase. The reason this is significant comes from the fact that shelter accounts for 33% of the total CPI basket of prices, the largest component.
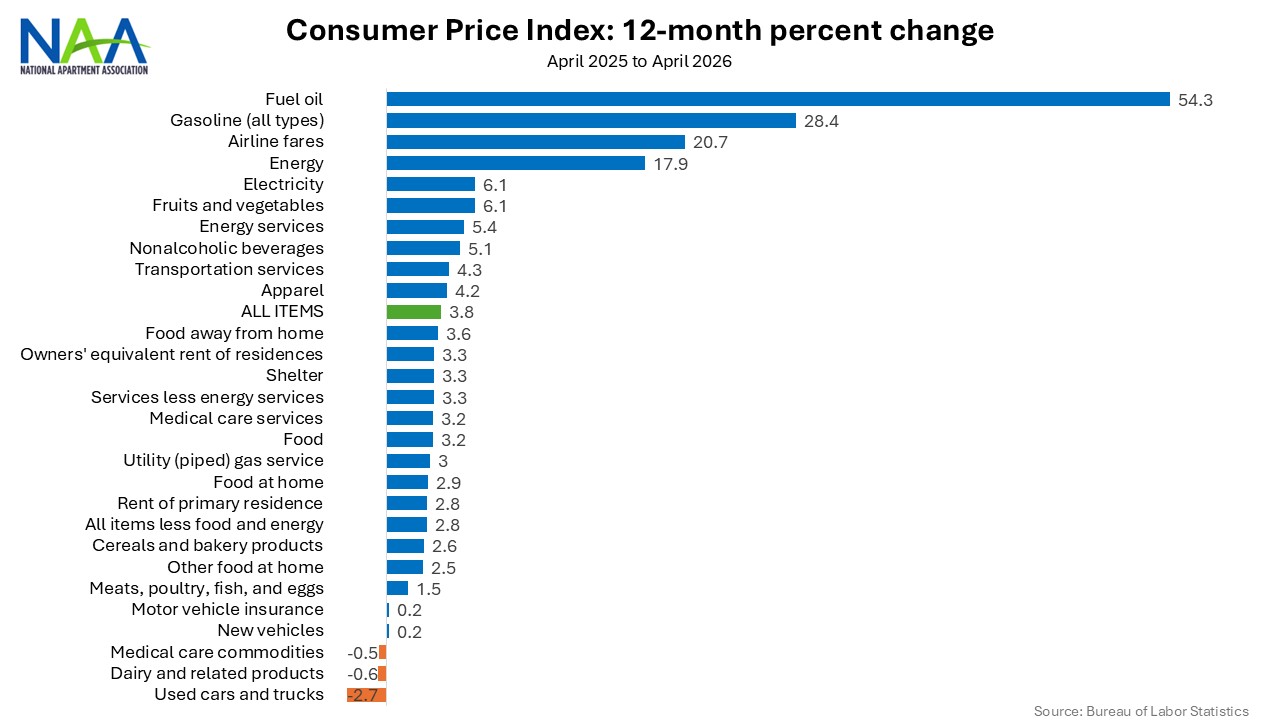
Several other price categories also saw notable year‑over‑year increases, including apparel (4.2%), food (3.2%), transportation services (4.3%) and medical care (3.2%). Used cars and trucks (- 2.7%) and medical care (-0.5%) were the only price categories which posted yearly declines.
Core inflation (excluding food and energy) rose 2.8% year‑over‑year, marking a slight acceleration from March’s 2.6%. These figures underscore that inflation is clearly moving away from the Federal Reserve’s 2% target, and even more importantly, adding increasing pressures on American’s monthly budgets at a time when wage growth is pulling back.
Wholesale prices also surge, signaling more cost pressures ahead
Upstream from the final prices consumer pay online or at the stores, wholesale prices—as measured by the PPI—showed even stronger inflation pressures. Producer prices rose 1.4% in April, the largest monthly increase since March 2022. On a year‑over‑year basis, the PPI climbed 6.0%, also the fastest pace in more than two years.
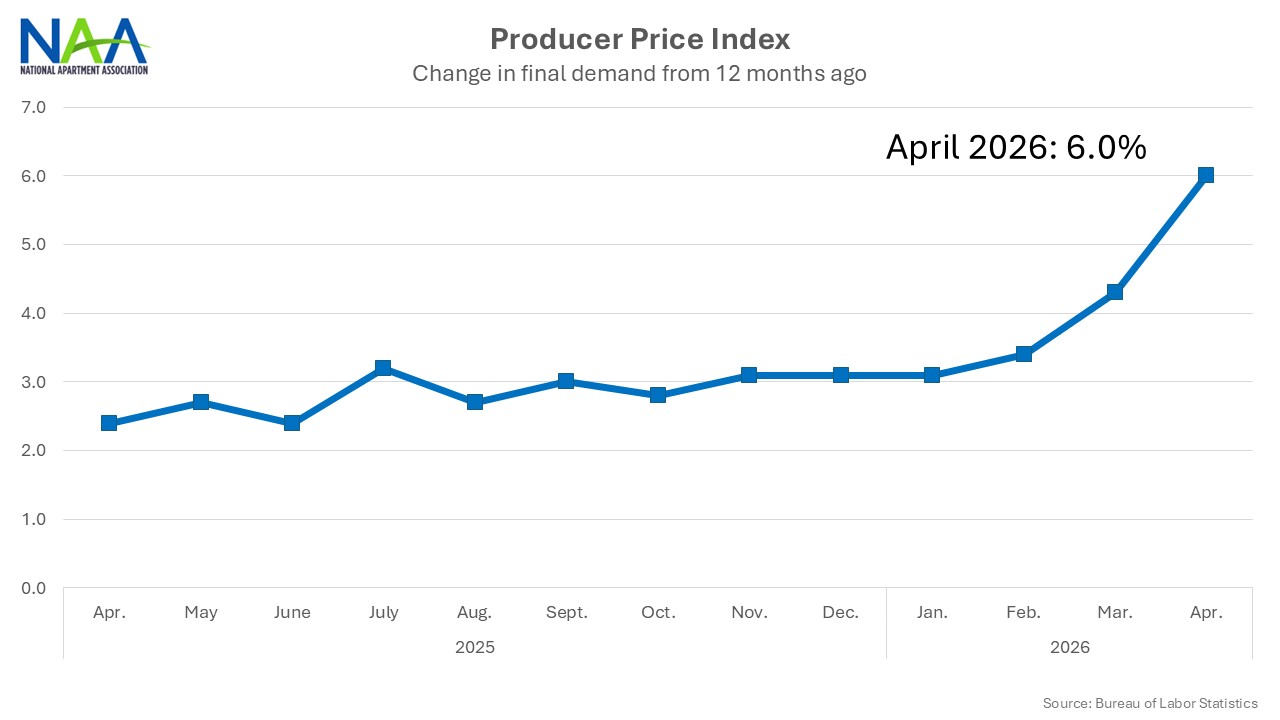
The main contributor to the jump in producer prices came from the 1.2% increase in the index for final demand services. The final demand index measures the average change in prices charged to consumers, businesses making capital investments, government, and exporters. This is a key measure of what we can expect to see at the retail level and likely showing up in the CPI down the line.
The April PPI increases reflect rising costs for transportation, fuel, chemicals, and other industrial inputs — pressures that often pass through to consumer prices with a lag. For housing providers, elevated PPI readings suggest continued cost challenges in areas such as building materials, maintenance supplies, and contracted services.
Implications for housing: resurgent mortgage rates and declining consumer spending power
The renewed inflation momentum has several direct implications for the housing market. The first is tied to mortgage rates, which are closely linked to inflation expectations and the trajectory of the 10-year Treasury. Financial markets closely watch inflation data when pricing Treasury yields and mortgage‑backed securities. With both CPI and PPI surprising to the upside, expectations for Federal Reserve rate cuts have been pushed further out.
After dropping to a low for the year of 3.96% on February 27, the 10-year Treasury rebounded following military action in Iran, closing in on 4.5% this week. In tandem with the rebound, the Freddie Mac 30-year fixed mortgage rate also reversed its downward trajectory. With spring signaling the start of the homebuying season, elevated mortgage rates, combined with high prices, will keep affordability out of reach for many buyers.
The second implication of rising inflation is tied to rising operating costs for many housing providers. Energy‑related inflation — particularly electricity and fuel — directly affects property operations. Rising wholesale prices for materials and services are likely to filter into higher repair, maintenance, and capital improvement costs.
Another effect of rising prices concerns the construction and development pipeline. With intermediate goods inflation running hot, developers may face renewed cost escalation in materials such as plastics, resins, chemicals, and transportation services. This could slow new supply pipelines or shift project timelines.
Key takeaways
The April inflation data mark a clear pivot in the economy, signaling that price pressures are no longer cooling but re‑accelerating. With consumer inflation rising at its fastest pace in over a year and producer inflation hitting multi‑year highs, the economic environment is shifting toward firmer inflation and tighter financial conditions.
This development adds significant constraints on the Federal Reserve’s monetary policy actions. Last year’s three rate cuts risk looking premature in an era of rebounding inflation.
For the housing sector, rising inflation means that we can expect elevated mortgage rates for the remainder of 2026. As the spring season unfolds, housing providers and developers will need to navigate an environment where inflation remains a central economic force, shaping consumer behavior, investment decisions, and market dynamics across the industry.